Bundled Insurance in Turkey: The New Rules That Protect You at the Checkout
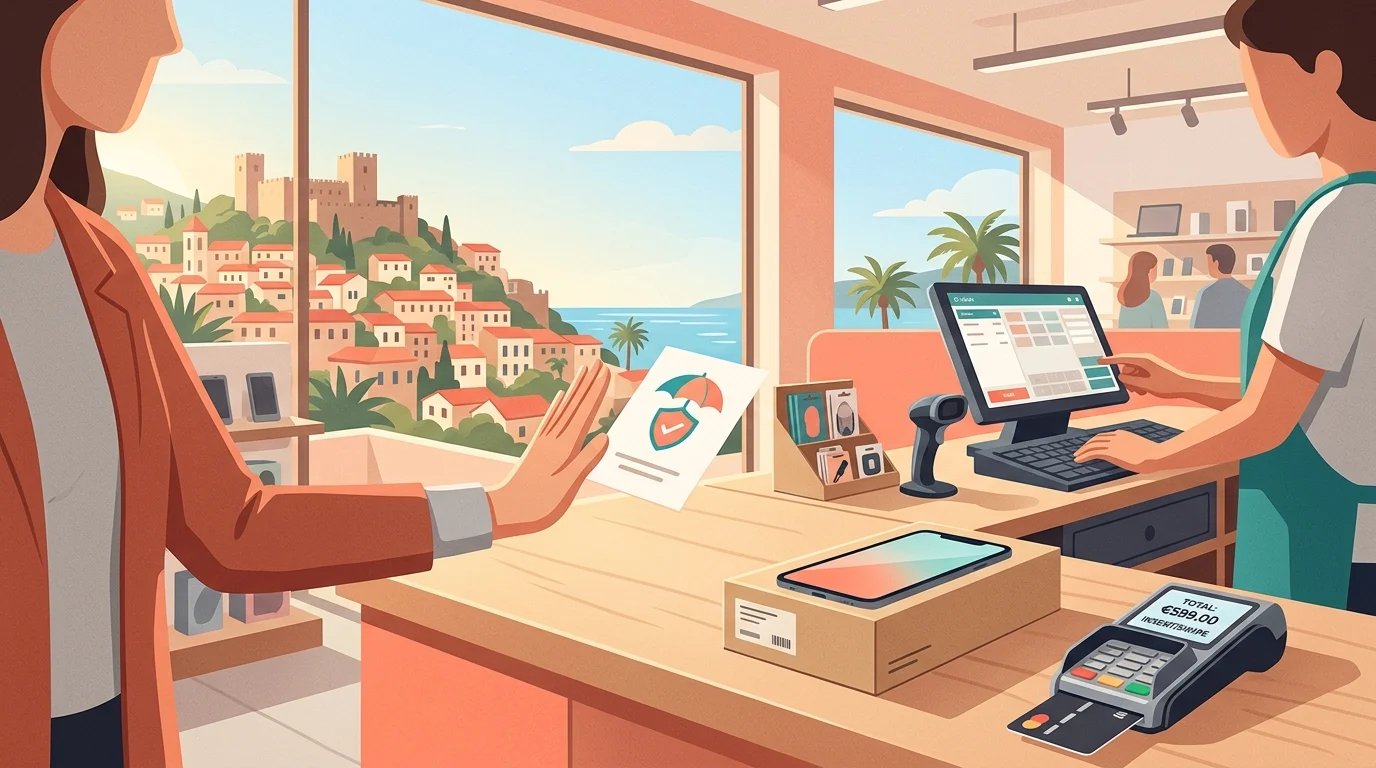
If you’ve ever been asked “would you like to add insurance?” when buying a phone, a household appliance or a holiday package, that question is now subject to strict new rules. The Insurance and Private Pension Regulation and Supervision Authority (SEDDK) has introduced a dedicated regulation on bundled insurance, published in the Official Gazette (issue 33428) on 12 November 2026 and in force from that date. Under the new rules, no seller can make a sale conditional on you taking out insurance, charge you more for refusing it, or bundle policies with no connection to what you’re actually buying.
What Is Bundled Insurance?
Bundled insurance is any insurance product offered alongside the sale or rental of a good or service — whether in a physical shop or online. Familiar examples include screen-damage cover sold with a smartphone, breakdown protection with a white good, cancellation cover with a flight or hotel booking, and supplemental damage waivers offered when you hire a car for a few days.
The regulation ties bundled insurance strictly to risks that are directly linked to the specific good or service (or its financing). In practice, that means a retailer cannot wrap an unrelated insurance product into the deal just because you happen to be standing at the till buying a phone.
Which goods and services can include bundled insurance?
The main categories of cover that can be offered as bundled insurance are:
- Breakage, loss, theft, fire or mechanical failure of the item being sold or rented;
- Illness, theft or loss of a pet;
- Cancellation or interruption of travel, transport, accommodation, events, subscriptions or utility payment services, as well as cybersecurity cover and short-term or shared vehicle rental;
- Insurance that foreign nationals are required to present when applying for a residence permit or visa;
- Life, payment protection and personal accident insurance linked to consumer credit offered by banks on third-party e-commerce platforms (i.e. not the bank’s own website).
By contrast, compulsory insurance, home and commercial property insurance, savings or investment-linked policies, and agricultural, marine cargo and legal expenses insurance cannot be sold as bundled insurance. Compulsory motor third-party liability insurance, for instance, sits entirely outside this new framework.
Tying a Sale to Insurance Is Now Unlawful
The single most important consumer protection in the regulation is straightforward: a seller or landlord cannot make the sale or rental of a good or service conditional on you taking out insurance. If you say no to the policy, you must still be able to buy the product on exactly the same terms — same price, same instalment plan, same delivery conditions. Offering you a worse deal just because you declined the insurance is explicitly unlawful.
This is particularly significant for hire-purchase and instalment transactions. Linking a retailer’s instalment sale campaigns to an insurance requirement now falls squarely on the wrong side of the law.
When can insurance be offered?
Bundled insurance can be offered at the point of sale or rental, or within 14 days of the contract being concluded. This is not a right of withdrawal window — it is simply the period during which the offer can lawfully be made. When the offer is made, you must be clearly told the name of the insurer, any intermediary involved, the premium amount and what the cover actually includes. It is also prohibited for the cover to be presented as though it comes from the retailer itself rather than from a regulated insurance or pension company.
Premium Cap and Maximum Duration
The regulation sets a cap on annual gross premiums for bundled insurance: the annual gross premium cannot exceed the monthly gross minimum wage in force during the first six months of the calendar year in which the cover begins. For 2026, the gross minimum wage is 33,030 TL (approx. £496 / €593 — depending on current exchange rates), so no bundled insurance policy starting this year may cost more than that in annual gross premium. The SEDDK Board can adjust this ceiling by up to 50% downwards or 100% upwards depending on the type of product or service.
Cover cannot last longer than two years. For extended warranty products, the duration may be aligned with the warranty period.
| Rule | What it means for you |
|---|---|
| Sale cannot be tied to insurance | You can buy or rent the item even if you refuse the insurance |
| No worse terms for refusing | Price, instalments and delivery conditions must stay the same |
| 14-day offer window | Insurance can only be offered up to 14 days after the sale |
| Annual premium cap | Maximum 33,030 TL gross premium in 2026 |
| Maximum two-year term | Extended warranty cover may run for the warranty period |
| Premium shown separately | The insurance cost must appear as a separate line on your receipt or invoice |
Ending the Contract and Proof of Payment
You can cancel a bundled insurance policy through the same remote channel you used to take it out, or through the authorised organisation. A seller cannot impose a harder cancellation route — for example, requiring you to visit a branch in person to cancel a policy you bought online.
If the underlying sale or rental contract is cancelled, you exercise your right of withdrawal, the contract is terminated or it otherwise ceases to exist, the linked bundled insurance automatically comes to an end as well. No compensation or penalty can be demanded from you as a result.
Where the premium is collected together with the price of the good or service, it must be shown as a separate item on the payment document. If it is collected separately, a separate receipt must be issued. The obligation to issue a policy document remains in all cases.
Why This Matters in Alanya — Especially for Foreign Residents
In Alanya, where the tourism and property markets are particularly active, the new rules have some clear practical effects:
- Holidays and car hire: Cancellation and damage cover can still be offered alongside tour packages, hotel bookings and short-term car rentals — but the booking itself cannot be made conditional on you taking out that cover.
- Electronics and appliances: Screen, breakdown and theft cover remains available as an optional add-on; the premium must appear as a separate line on your receipt.
- Foreign residents: Insurance required for residence permit and visa applications can be provided as bundled insurance under this framework. Any service provider who makes their service conditional on you purchasing insurance through them specifically would be acting unlawfully under these rules.
What to do if you encounter a breach
If a seller tries to make a sale conditional on insurance, or charges you a higher price because you declined, keep all the evidence — receipts, screenshots of promotional pages, and any written or electronic correspondence. For disputes with retailers, the Consumer Arbitration Committee (Tüketici Hakem Heyeti) and the Consumer Court (Tüketici Mahkemesi) are the main routes. For disputes with an insurer over the cover itself or a premium refund, the Insurance Arbitration Commission (Sigorta Tahkim Komisyonu) may be more appropriate. The right route depends on who the dispute is with and how much is at stake.
What Sellers and Intermediaries Need to Do
Shops, e-commerce platforms, travel agents and rental companies acting as authorised organisations under this regulation are responsible for the security of their IT systems and integrations, maintaining transaction records, and ensuring that premium collection complies with the rules. Crucially, they must notify SEDDK at least one month before they start offering bundled insurance. Reviewing existing checkout flows, promotional copy and point-of-sale processes against the new requirements now is the most effective way to reduce the risk of enforcement action.
The same Official Gazette also amended the Regulation on Activities to Be Considered within the Scope of Insurance and on Distance Insurance Contracts; the previous provisions on bundled products were repealed and references redirected to the new Bundled Insurance Regulation (Bütünleşik Sigortalar Hakkında Yönetmelik).
This article is for general information only and does not constitute legal advice. For your specific situation, always refer to the current legislation and official announcements.
Frequently Asked Questions
Answers to the questions on your mind